You’ve spent 25 years learning how to save. Now you need a plan built for spending it.
We’re fiduciary retirement income planners with offices in Ankeny, Clear Lake, and Humboldt. For two decades we have been building retirement income plans for clients nationwide. We do one thing: turn what you’ve saved into income that lasts — through market downturns, tax changes, and thirty years of retirement.
71%
of consumers say recent market volatility has changed how they think about retirement —
not just how they invest today, but what they expect retirement to look like. *
65%
of non-retirees don’t think their retirement savings plan is on track —
the question that keeps people up at night is “will this last as long as I do?” **
*Source: PwC
**Source: Federal Reserve Board
A downturn shouldn’t be the first time we talk about what happens in a downturn.
Here’s the actual plan — not a promise that markets won’t drop, but what happens when they do.
- 1
Structure: Income is split by when you’ll need it
Near-term spending sits in stable holdings. Long-term money stays invested for growth. A down market never forces you to sell at a loss to cover this month’s bills. - 2
Rules, set in advance: Withdrawal guardrails, decided early
We set clear triggers for adjusting withdrawals while markets are calm — not while you’re watching the news and deciding under stress. - 3
Testing: Your plan is tested against real history
We model it against 2008, 2020, and 2022 — actual downturns, not an average return smoothed over thirty years. - 4
Communication: You hear from us when it matters
A call from your advisor, not a quarterly statement. If nothing needs to change, we tell you that too.
Growing a portfolio and living off one are not the same discipline.
Most financial advice is written for accumulation: save more, diversify, ride out the dips. That’s good advice in your thirties and forties. But turning savings into retirement income takes a different method — a different set of skills entirely.
We focus on retirement income. Not a model portfolio you check on twice a year, but an actual income plan: what you’ll draw each year, from which accounts, in what order, and how that holds up through a bad market, a tax law change, or an unexpected expense. Growth still matters, but it’s in service of the income, not the other way around.
RMDs are where most tax conversations start with us. They’re not where they end.
Required Minimum Distributions come up a lot in our work — timing the first one, sizing withdrawals to avoid a higher bracket, avoiding penalties. But an RMD is one number, calculated once a year. A real tax strategy decides whether that number is a problem, and it has to start years before age 73, not after.
Becoming a client is a process, not a pitch.
Here’s exactly what happens, start to finish.
An introductory call
We ask what you’re trying to solve. You ask us anything. We’ll tell you plainly if we’re a fit before either of us commits more time.
We help build your plan
We gather your accounts, income sources, and goals, then help build a specific plan: income sequencing, a tax map, and a downturn plan — not a template.
We walk through it together
You leave with a written plan and a clear answer on whether we’re the right fit going forward.
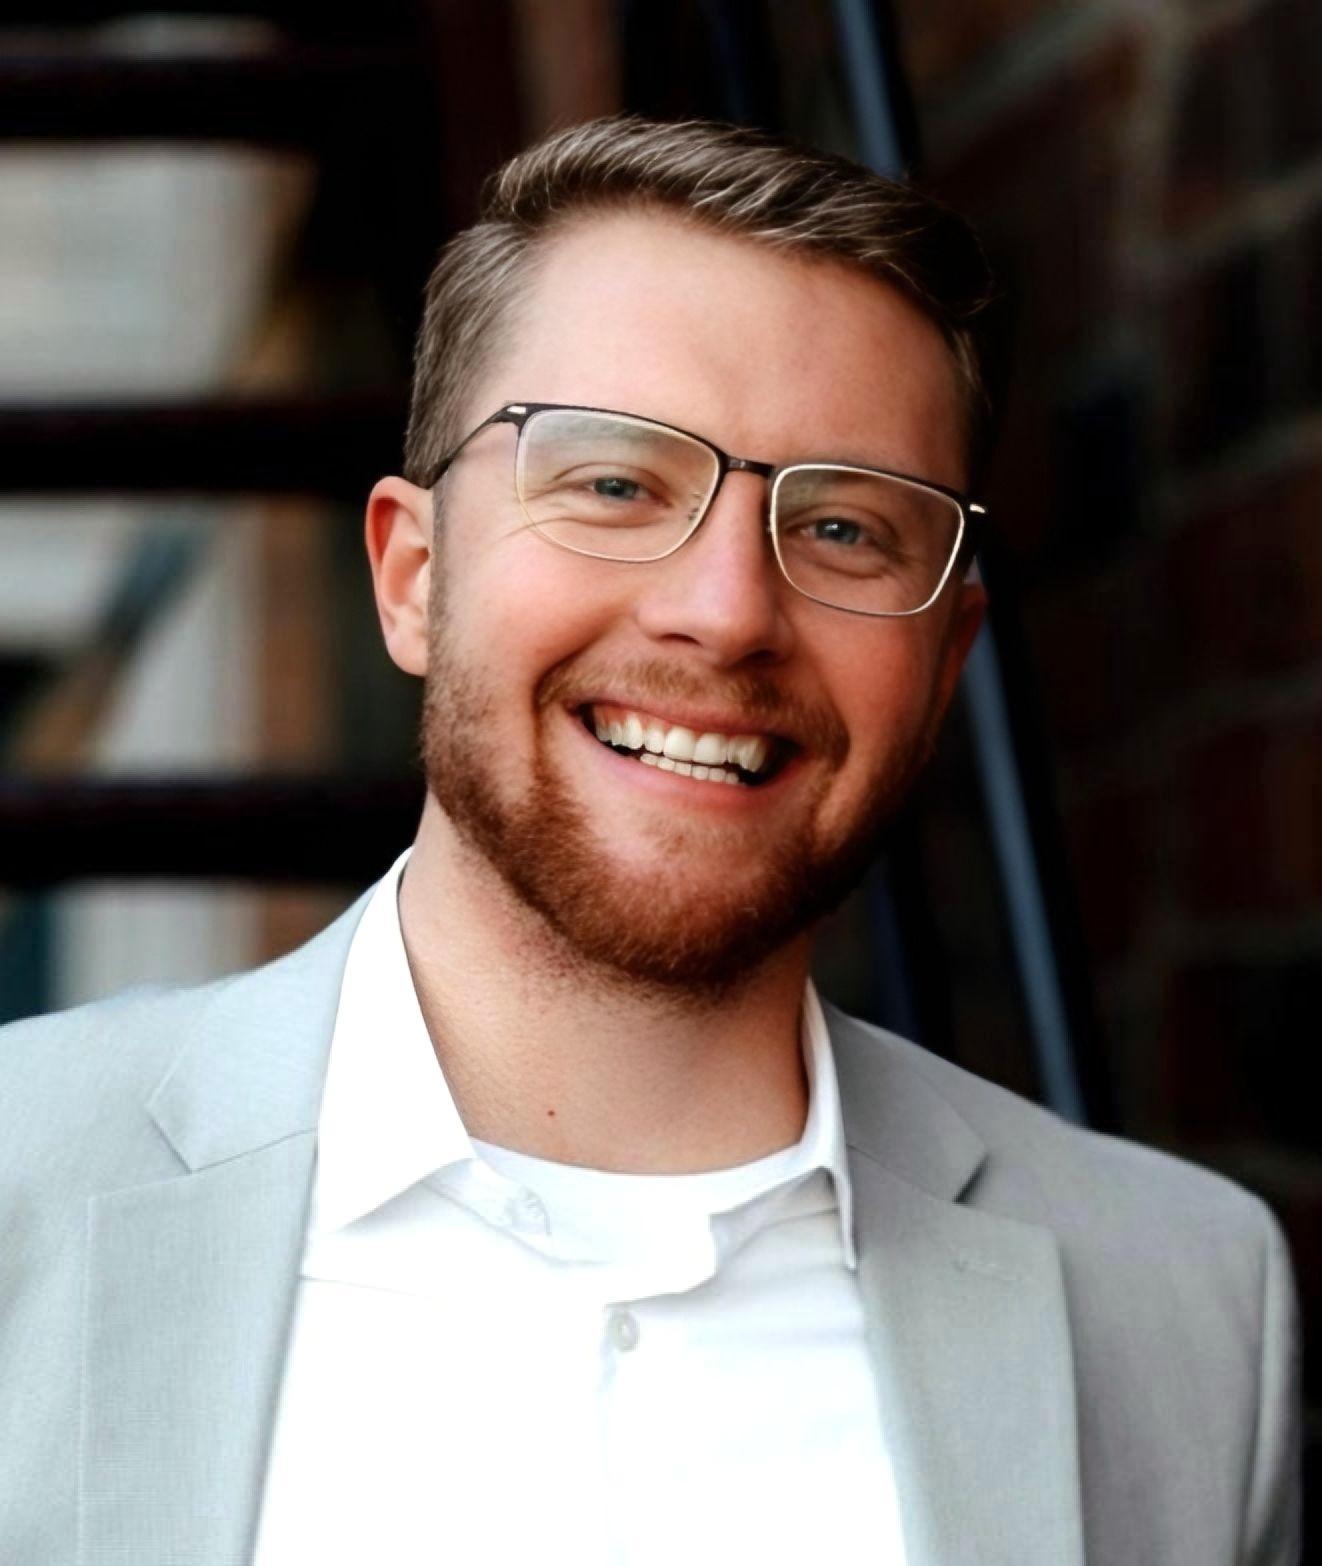
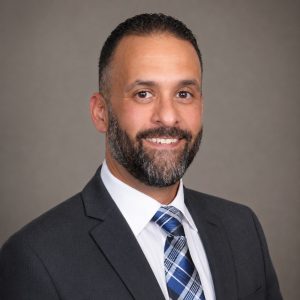
Experienced Investment Guidance
Our investment advisors help you make thoughtful decisions, so your investments support your long-term financial goals.
A Member of Retirement Income Source
Johnson Wealth & Income Management is a proud member of Retirement Income Source, a national network of financial advisors who specialize in income-generating investment strategies designed to help protect retirement savings.
Through this network, our advisors have access to research, strategies, and resources focused on helping retirees develop reliable income streams designed to support financial peace of mind throughout retirement.
Get Social Security wrong, and there’s no do-over.
Claim too early and you lock in a smaller check for life. Ignore the tax side and up to 85% of your benefit can end up taxable. Skip coordinating with your spouse, and a surviving spouse can end up with far less than they should have. These are the questions we hear most — and the ones we plan around before you file, not after.
Claiming Too Early
Filing at 62 can lock in a permanently smaller check — often costing tens of thousands over a lifetime
Surprise Taxation
Up to 85% of your benefit can be federally taxable if the rest of your income isn’t planned around it
A Spouse Left Behind
The wrong claiming strategy can leave a surviving spouse with a smaller check for the rest of their life
Source: Social Security and Equivalent Railroad Retirement Benefits